The opportunity · lastnamedomains.com
lastnamedomains.com
A specialist brand in a market everyone else treats as generic: the free, name-aware domain search is built and working — this page makes the case for why that brand, that market, and this app form a strong opportunity now.
At a glance
Four facts, each sourced
Why this domain
The name does half the marketing
- Length & form
- Two familiar words, 16 characters, phonetic, one obvious spelling
- Category fit
- Exact compound of the niche’s two highest-intent words
- Extension
- .com — the default audiences trust and type
- Brandability
- Reads as a category name: “the lastname domains specialist”
- Social handles
- @lastnamedomains unregistered on X and GitHub (checked 2026-09-24); other platforms partially verified
- Comparables
- Personal-name domains typically trade low-four-figures; market-wide, 205k+ recorded sales in 2026 [3][4]
Memorability and fit. The domain is the exact compound of the two words customers in this niche actually use — nobody needs it explained, and it reads naturally in a sentence (“search lastnamedomains.com”). The .com extension carries the trust default, and the name extends cleanly to adjacent offers (family identity, name reports, a builder). Matching social handles were available on the platforms checked on 2026-09-24 (method in Sources [9]).
Comparables, not a valuation. Domain sales are public enough to contextualise, and noisy enough that honesty matters: 205,445 sales of $100+ were recorded market-wide in 2026 to date, totalling ≈$214.8M [3]; headline 2024 sales reached $14M for Rocket.com [4] — a different tier entirely. Personal-name domains rarely make headline charts and typically trade in the low thousands of dollars [4][5]. Those figures are context for the market's liquidity, not a claim about this domain's price. Registration is verifiable (expiry 2026-11-07); ownership is not asserted here.
Why this market, and why now
Large, growing — and unserved at the personal layer
Total vs reachable. The total market is every domain registration decision — hundreds of millions a year [1][2]. The reachable launch segment is narrower and honest: people searching their own or their child's name — a documented, recurring behaviour [5][6] — in English-speaking markets, at first. No credible TAM figure exists for “personal-name domains”, and we will not invent one.
Why now. The data layer finally makes a specialist tool possible with zero marginal cost: open registry RDAP and keyless DNS-over-HTTPS allow real availability checks from the browser — no API keys, no per-query cost. That infrastructure did not exist in this form when the generic tools were built; it is the opening.
The customer problem
Generic tools treat your name as a keyword
Professionals, new parents, and families all eventually search their name against a domain. The workarounds today: type guesses one at a time into a registrar, run a keyword tool that treats john-smith.com and jsmith.com as unrelated strings, then hit a dead end when the .com is taken — no path, no context, no help. The cost is small per event but recurring and emotional: it is your name.
The product — built and working
Try it in the next sixty seconds
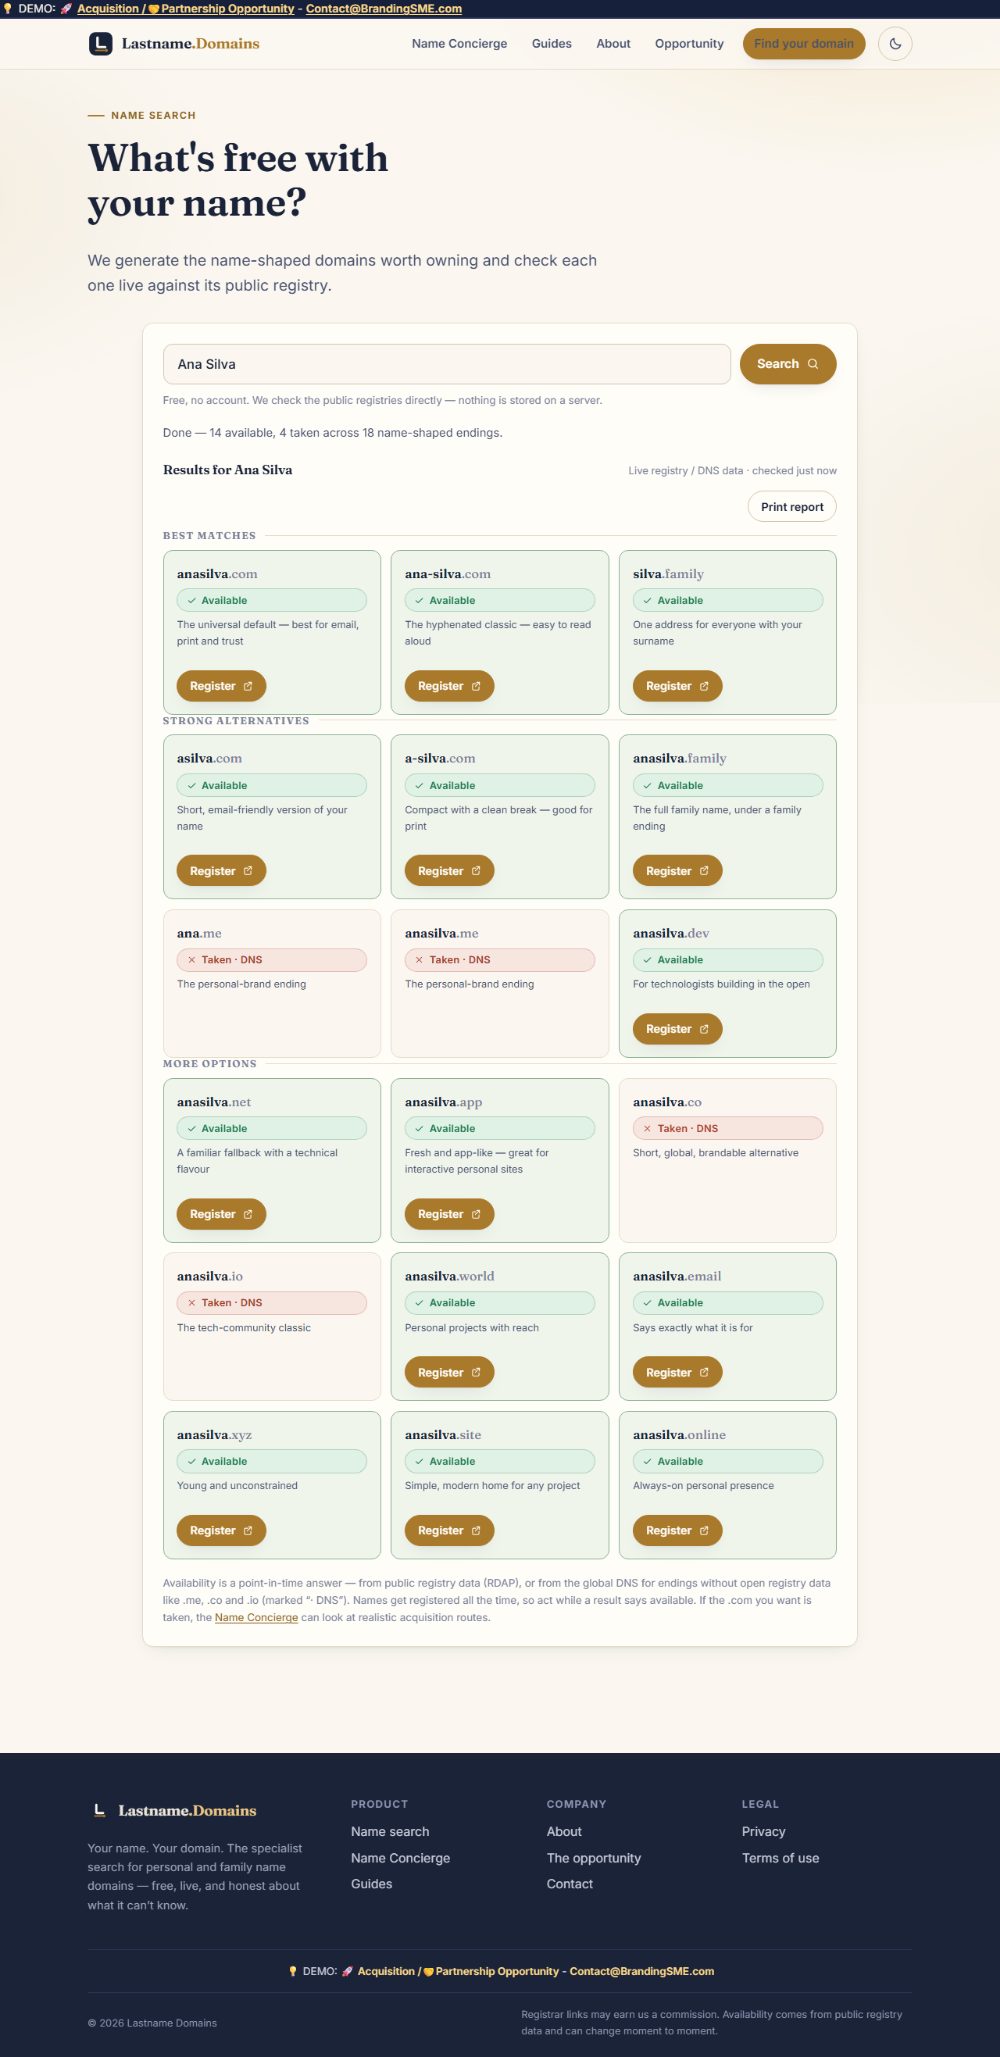
Delivered and working on real data: the name-aware search (12 RDAP endings + 3 DNS-checked), the Name Concierge enquiry path with an Internet Archive history helper, and three sourced guides. Open the live search or see the concierge — everything on this page links into the working product, because the product exists.
Why this app can win
Positioning, win themes, defensibility
Win themes (measured against Instant Domain Search, Domainr, and registrar searches — comparison method [10]): time to a useful result across the whole shape of a name; clarity and trustworthiness of the output (sources named, DNS-based results labelled, failures never guessed); and the taken-name path — concierge and archive history where others stop at “taken”. Parity: free access and one-click registrar hand-off.
Defensibility, honestly: the tool alone can be copied; the compounding assets are the specialist brand, the content moat, the concierge relationships, and search position in a niche no incumbent has bothered to claim. Those are claims about strategy, not current traction — there is no traffic or revenue yet, and this page will not pretend otherwise.
Business model · go-to-market · scenarios
Capital-light, evidence-gated
Model (proposals, not prices). Revenue starts with registrar commissions — around 20% of a registration is the published industry rate [7] — then concierge acquisition referrals sharing the 10–30% marketplaces charge [8]. No checkout, no fees quoted, until the owner approves real pricing.
Go-to-market. Primary: search-intent content (the three live guides). Secondary: honest participation in parenting and personal-branding communities. The opportunity page itself serves the distinct investor/partner/acquirer audience — deliberately separate from the customer funnel.
Scenarios below are projections with editable assumptions — not forecasts of results. Base case assumes 10,000 searches/year at 5% registrar click-through and $4 average commission; full table and sensitivities in the run record.
| Scenario (12 months) | Searches | CTR | Revenue (projection) |
|---|---|---|---|
| Conservative | 2,000 | 2% | ~$150 |
| Base | 10,000 | 5% | ~$2,600 |
| Optimistic | 50,000 | 8% | ~$23,600 |
- Weeks 1–2 · done
Launch build
Search, concierge, guides, installable app — this site.
- Weeks 3–6
Measure & affiliate
CTR and enquiry metrics; registrar affiliate approvals.
- Weeks 7–12
Double down
Scale what converts; interview enquirers; gate the next layer on evidence.
What each audience gains
Three doors, one working product behind them
Investors
A capital-light consumer funnel with commission revenue from day one and a working demonstration — not a concept. New capital, if ever sought, would unlock content scale and the concierge's next tier; terms and returns are never promised here.
Investment enquiryStrategic partners
Registrars, marketplaces and personal-brand platforms receive customers who already know exactly which name they want — pre-qualified, labelled traffic plus content partnerships.
Partnership enquiryAcquirers
What exists today and could be included: the lastnamedomains.com domain (registration verified; ownership verification with the owner), the complete codebase and tests, the design system and brand assets, the content corpus, and the run documentation. Nothing is claimed beyond that list.
Acquisition enquiryRisks — stated plainly
What would make this fail
- Demand risk. Visitors may search but not act. Measurable within weeks — which is exactly why the plan measures click-through and enquiries before anything else.
- Competition risk. A registrar could ship a name-aware search. The durable defence is the specialist brand, the concierge, and content depth — not the tool alone.
- Data risk. Live checks depend on registries' open RDAP and public DNS; coverage per ending is verified and shown, and anything unverifiable is routed to a registrar check instead of faked.
- Execution risk. The concierge is human work, capped at enquiry volume until its economics are proven.
All forward-looking statements are plans and projections, not results. No revenue, traffic, or customer figures are claimed before they exist.
Interested in the brand, the build, or the domain?
One inbox, read by the owner. The buttons above and below open a pre-addressed email — the browser cannot confirm delivery, and we never claim it did.
Sources and method
Every figure, traced
- Verisign Domain Name Industry Brief, FY2025 (386.9M end-2025), via NamePros coverage, February 2026 — accessed 2026-09-23.
- Verisign DNIB Q2 2026 (401.6M), via industry coverage — accessed 2026-09-23.
- NameBio “Top 100 Domain Sales of 2026” chart: 205,445 recorded sales of $100+, ≈$214.8M total — namebio.com, accessed 2026-09-24.
- DNJournal 2024 Top 100 Domain Sales (Rocket.com $14M; personal-name context) — dnjournal.com, accessed 2026-09-24.
- Fox News, “Smart parents can secure their child's digital identity”, May 2025.
- New York Post coverage of a 2018 millennial-parent survey (45% name-reservation figure); survey methodology not independently verified — treat as directional.
- Namecheap affiliate commission schedule (20% domains) — namecheap.com, checked 2026-09-23.
- Afternic 25–30% and Sedo ~10–20% marketplace commission ranges — public pricing pages and comparison coverage, checked 2026-09-23.
- Registration facts: Verisign RDAP record for lastnamedomains.com (expiry 2026-11-07) — queried 2026-09-23. Social handles: public profile URL checks (HTTP 404 = appears unregistered) on X and GitHub — checked 2026-09-24; TikTok/Reddit inconclusive by automated check.
- Competitive positioning built from our own observed task comparison (Command 03 of the build run), not vendor marketing.
Derived figures (scenarios, revenue projections) are our own models with assumptions shown; they are projections, not results. This page is an invitation to enquire — it is not an offer of securities, and no return is promised or implied.